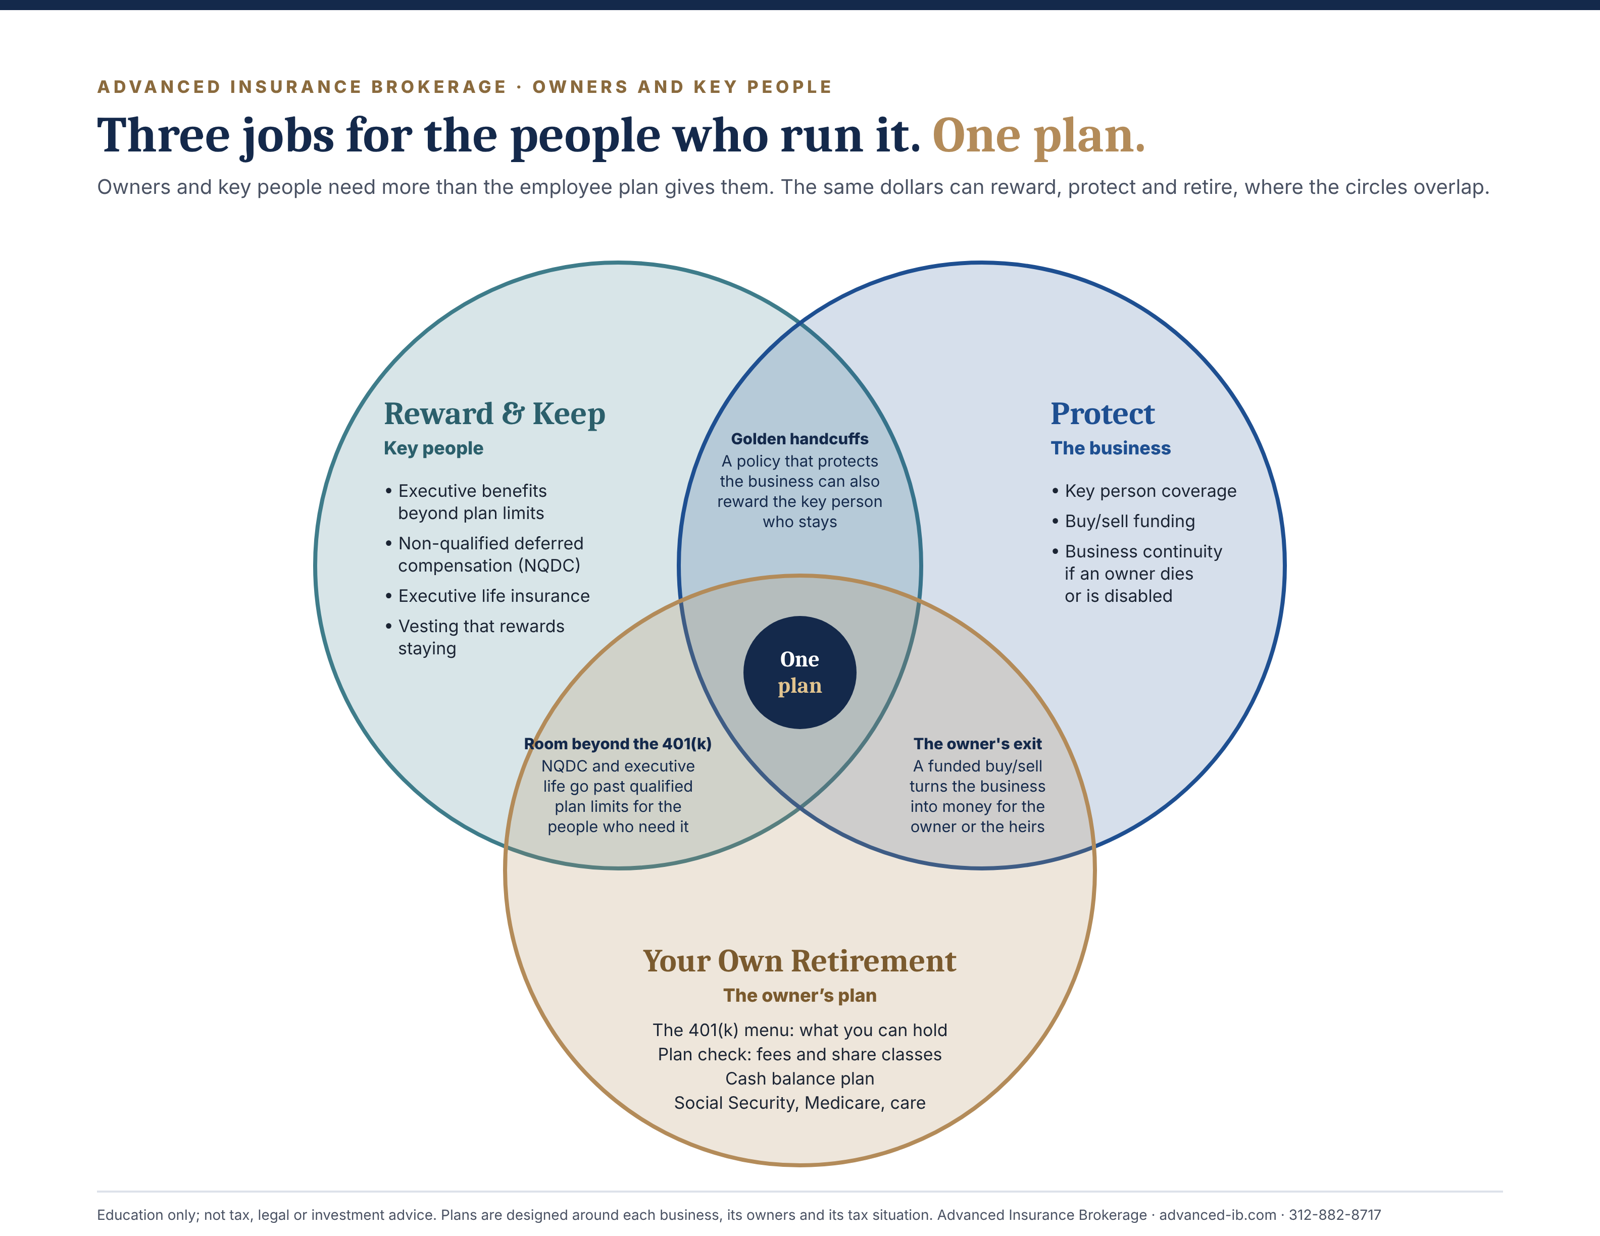
Three jobs for the people who run the business. One plan.
Reward and keep key people, protect the business, and plan your own retirement. The same dollars can do more than one job, and the overlaps are where planning pays.
 Open the diagram (PDF) →
The people who drive the business are the hardest to replace. Benefits beyond the 401(k) give them a reason to stay.
- Executive benefits beyond qualified plan limits
- Non-qualified deferred compensation informally funded with company-owned permanent life insurance
- Executive life insurance with cash value that can supplement retirement income
- Vesting that rewards the key person who stays
If an owner or key person dies or is disabled, the business needs money and a plan on day one.
- Key person coverage against the loss of an owner or key employee
- Buy/sell funding so owners or heirs are paid and the business continues
- Policy review: see whether coverage bought years ago still fits
- Advanced Services: owner and key-person policies designed and compared
Owners often have the largest balances and the least room in the plan they sponsor.
- The 401(k) menu: what your plan lets you hold, and why
- The brief: Built for Everyone: Why Your 401(k) Stops at Funds
- Plan check: fees, share classes and the brokerage window
- Social Security, Medicare and care for the owner and spouse
Education only; not tax, legal or investment advice. Plans are designed around each business, its owners and its tax situation.
Tailored plans built on permanent life insurance
When designed for it, cash value life insurance can fund benefits that a qualified plan can't. Each plan is designed around the business, its owners and its tax situation.
Executive benefits
Reward and retain key people beyond qualified plan limits, with cash value that can supplement retirement income.
Non-qualified deferred compensation
Informally fund a deferred compensation promise with company-owned permanent life insurance.
Key person coverage
Protect the business against the loss of an owner or key employee, with tax-deductible or pre-tax options where available.
Buy/sell funding
Fund a buy/sell agreement so owners or heirs are paid and the business continues.
Your 401(k) was built for everyone. That’s the problem.
Most 401(k) platforms offer a short menu of pooled products: mutual funds, target-date funds and collective trusts. The average menu has about 17 funds, and most employees use two. That works for a 30-year-old with a default election. It works less well for an owner or key employee with a large balance who wants to hold individual stocks, a Treasury ladder or bonds held to maturity.
Why the menu looks that way
The platform is paid on pooled assets
Many recordkeepers are paid through fees built into fund expense ratios (revenue sharing) or through their own funds. An individual stock or bond held for years produces little of that ongoing revenue.
You carry the fiduciary risk
Every option on the menu is one you must choose prudently and keep monitoring. Fewer, pooled options are easier to defend, and even brokerage windows have drawn Department of Labor attention.
Defaults protect most employees
Target-date funds are offered in 96% of plans and are the default in nearly all of them. They keep most savers diversified.
What we review
- ✓Does your plan have a brokerage window, and what can it hold: funds only, ETFs, stocks, bonds?
- ✓How is the recordkeeper paid: revenue sharing inside the funds, a per-person fee or a percentage of assets? Who pays it?
- ✓Are you in the lowest-cost share class or collective trust available for your plan size?
- ✓Would a cash balance plan, non-qualified deferred compensation or executive life insurance give key people more room than the 401(k) can?
 Plan sponsor brief · 4 pagesBuilt for Everyone: Why Your 401(k) Stops at FundsThe market, the menus, how platforms are paid, and a case study: the owner who wanted a bond ladder.Read the brief (PDF) →
Education only; not investment, tax or legal advice. Figures: Vanguard, How America Saves 2025 (year-end 2024 data); Alight brokerage window data (2021); PLANSPONSOR 2026 Recordkeeping Survey.
Plan for the people who run the business
A short call covers the owners, the key people and what the business needs to protect.