Three stages of a career. One benefits plan.
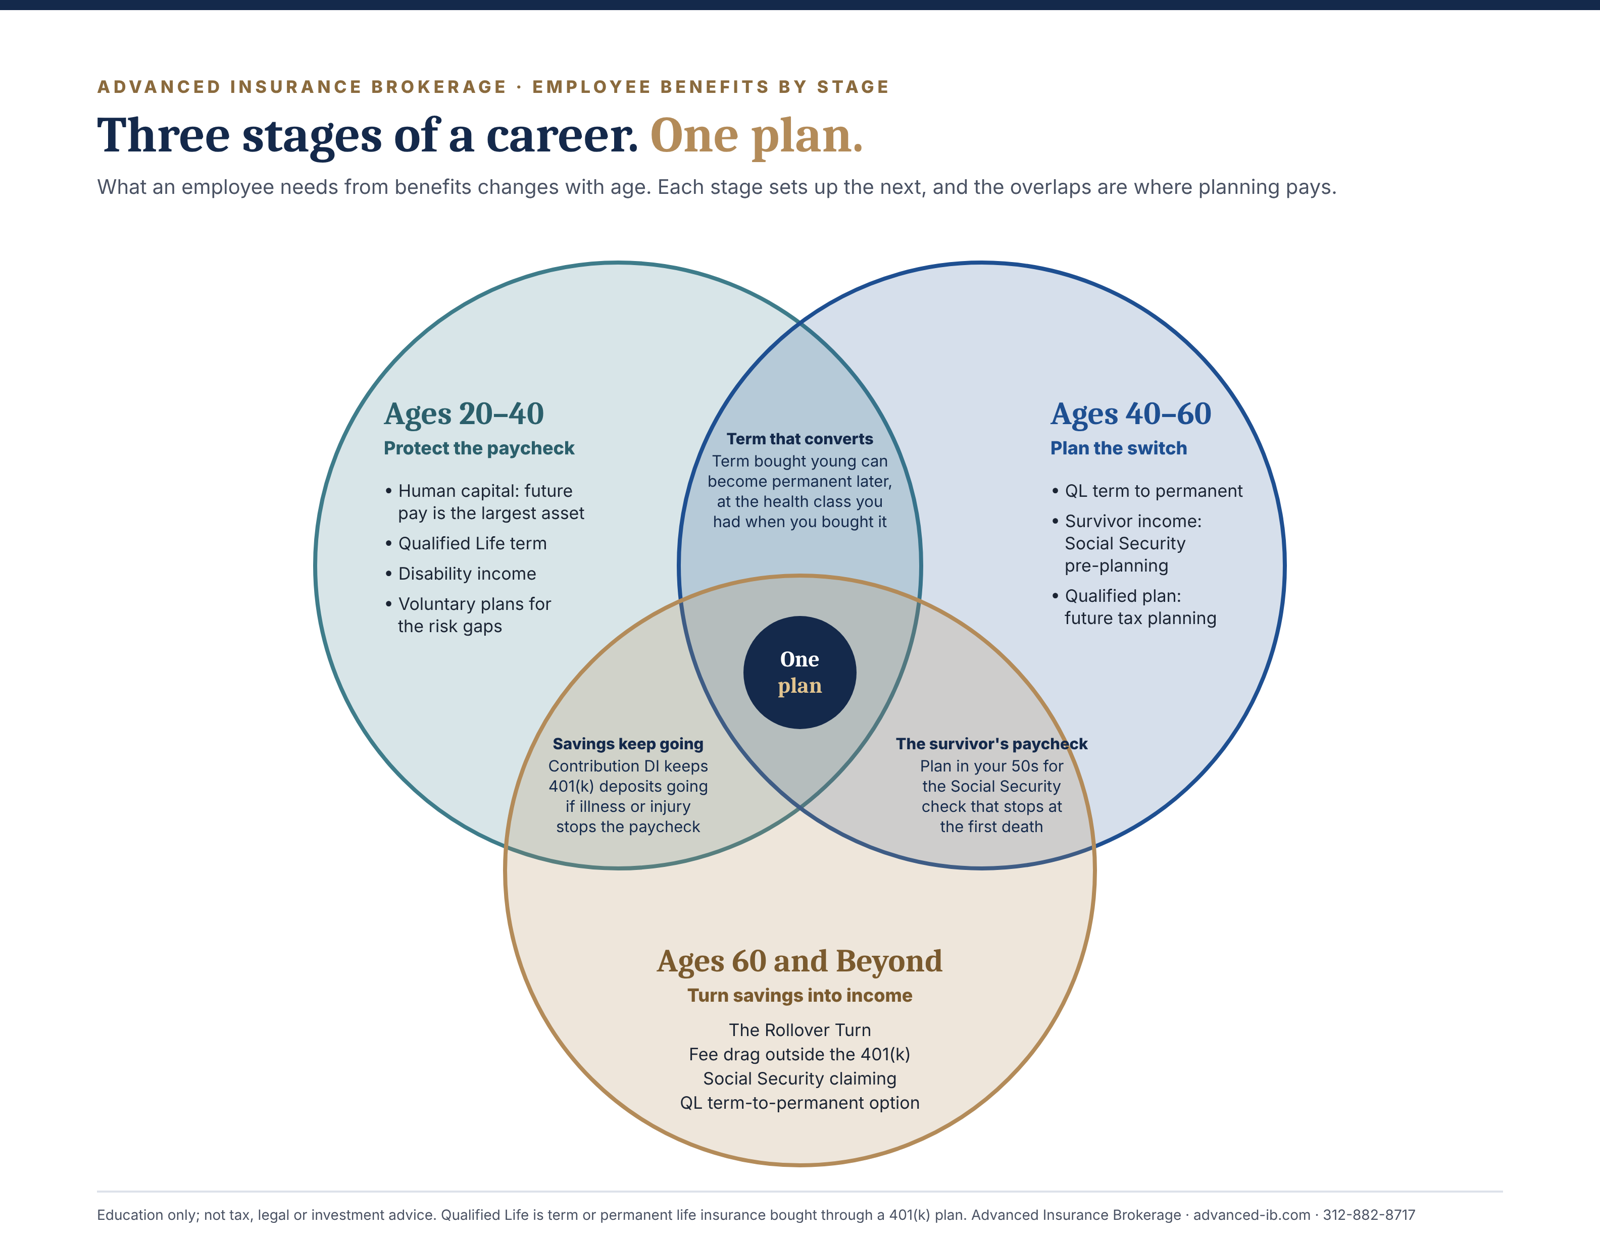
What an employee needs from benefits changes with age. Find where each group of your employees sits, and see what we offer at each stage. Each stage sets up the next, and the overlaps are where planning pays.
 Open the diagram (PDF) →
At this age the largest asset an employee has is the pay still ahead of them: their human capital. The job is to insure it.
- Human capital: life coverage sized to income-earning potential, not just the mortgage
- Qualified Life term through the 401(k), paid with pre-tax dollars
- Disability income: Contribution DI keeps pay and 401(k) deposits going after an illness or injury
- Voluntary benefits that fill the risk gaps: accident, critical illness and hospital coverage
Peak earning years. Coverage, Social Security and the 401(k) each need a plan for what comes next.
- Qualified Life term to permanent: convert at the health class you have now, before your health changes
- Social Security pre-planning: survivor income, so the household is ready when one check stops
- Qualified plan tax planning: pre-tax, Roth and what the tax bill looks like at withdrawal
The decisions now are about income, fees and timing, and most of them can only be made once.
- The Rollover Turn: what moving the 401(k) to an outside account can cost
- Fee drag outside the 401(k): what higher fees take from the same savings
- Social Security claiming: 62, full retirement age or 70, as a couple
- Qualified Life term-to-permanent option before the conversion window closes
- Medicare and long-term care: see the Retirement after 60 service below
Education only; not tax, legal or investment advice. Qualified Life is term or permanent life insurance bought through a 401(k) plan.
Qualified Life: coverage through the 401(k)
Bought on your own, a $1,000 term premium takes about $1,429 of pre-tax pay. Through the plan, the employee's net cost in our example is $596.
See the employee guides: Part I (Death Benefit) and Part II (The Redirect).
- Pre-tax or tax-deductible premiums
- Unisex rates, up to 10% lower (varies)
- Employer match where the plan offers one
- Spousal coverage and conversion to permanent coverage
Same dollars, new direction
The employee was paying $1,000 a year for retail term coverage. With Qualified Life, they stop writing that check to the old insurance company. The same pay goes into the 401(k) as a Traditional (pre-tax) contribution instead, and the plan pays for the coverage.
See both case studies: Part I: Life Insurance Inside Your 401(k) (Qualified Life only) and Part II: The Redirect (with the Contribution DI).
Want to check the numbers? Part III: The Math Behind Qualified Life itemizes every dollar, shows results with no employer match, and includes a worksheet. Or try the Term Premium Tax Calculator → To see what the savings are worth over time, read Advanced Group's What $1,000 a Year Is Really Worth.
Year-one example from the AIB Part I and Part II guides: $1,000,000 of term coverage, age 40, 30% tax rate, 10% unisex savings, an employer match of 100% of the first 3% (covering $450 of the premium) and carrier REB rates. Savings decline in later years as the taxable REB rises. The plan must permit life insurance. Results will differ.
The road map: from the first call to enrolled employees
Six steps, with AIB coordinating each one. Nothing in your plan changes before step 5, and you decide at step 4 whether to go ahead.
Download the Employer Road Map- 1AIB with your TPAPlan checkWe ask your TPA whether your plan document allows life insurance or needs a short amendment. Your plan stays where it is.
- 2AIBEmployer sampleA one-page look at what Qualified Life could mean for your company, using your plan averages. We send it to you directly.
- 3Your employees · 2 minutesEmployee surveyThe basic idea plus a few personal questions. We send you the link to share; answers come to AIB, not to you. Employees who ask get an estimate flow chart.
- 4AIBResults and suggestionsYour combined results with your actual match applied to each employee, and our recommendations. You decide.
- 5AIB, your TPA and trusteePlan setupAny amendment, plus carrier and trustee approval. AIB coordinates the paperwork.
- 6Employees and AIBEnrollment and serviceA short intake, a consultation to set each employee's coverage, applications and ongoing service, including REB figures.What employees get (Part I) →
Retirement planning after 60: three decisions, one plan
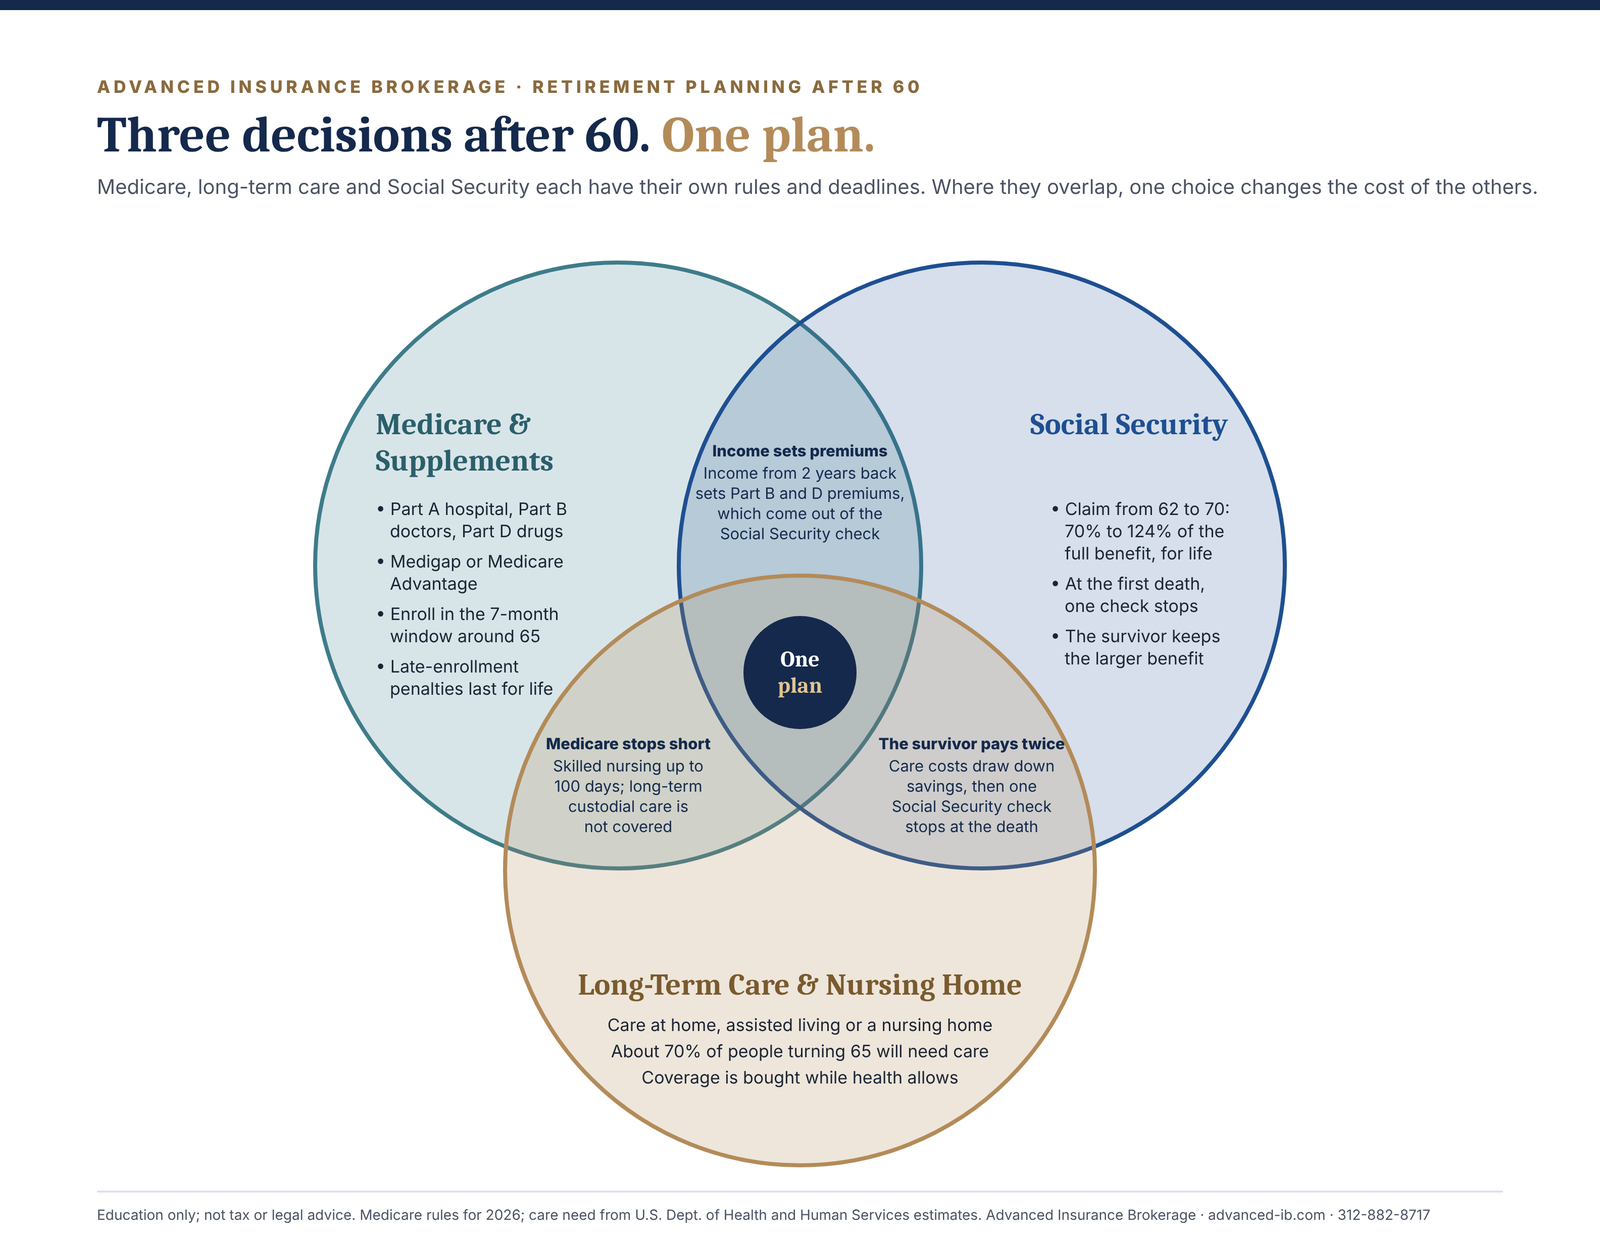
Employees in their late 50s and 60s face three decisions with deadlines: Medicare, long-term care and Social Security. Each one changes the cost of the others. We offer an education session and one-on-one reviews as an added benefit for the people closest to retirement.
 Open the diagram (PDF) →
What your employees get
- 1A group education sessionOn site or by video: how Medicare, long-term care and Social Security fit together, using the diagram.
- 2A one-on-one reviewEach employee who asks gets a private look at Social Security claiming as a couple, Medicare timing and a plan for care.
- 3Tools to use at homeThe Social Security calculator, the case studies and the Retirement after 60 guide.
Education only; not tax or legal advice. Individual reviews are optional and private to each employee.
Executive benefits, buy/sell and your own 401(k) have their own page
Reward and keep key people, protect the business, and plan the owner’s own retirement.
Keep your 401(k). We'll handle the plan check.
Qualified Life works with the plan you have. We'll ask your TPA whether your plan document allows life insurance or needs a short amendment. If they push back, we can shop that piece for you and show you what each part of your plan costs. You decide whether anything changes.
See what your plan could offer
A short call covers your plan, your workforce and which options fit.